Short, useful updates on the market, lending and making your money work harder. These are the updates we share on our socials, in one place, so you never have to scroll to find them.
The RBA has lifted the cash rate target four times in 2026, to 4.60% (source: RBA, rba.gov.au). Lenders test your loan at a higher rate than the one you would actually pay, so as rates rise the amount you can borrow may drop.
A pre-approval from a few months back might not match what a lender would say today, and every pre-approval has an expiry date. It is much better to find that out before the auction than after, so talk to us about a fresh check. General information only, not advice about your situation.
The ATO's general interest charge on tax debt is 11.51% a year from 1 October 2026. It compounds daily, and since 1 July 2025 it can't be claimed as a tax deduction.
A payment plan isn't the only way out. If you own property, it may be possible to clear an ATO debt with a loan secured against it. We look at the whole position first, then the options. Source: ato.gov.au, general interest charge rates. General information only, not advice about your situation.
Duty First is not just a business name. We are veteran owned, and the word duty is deliberate. Your file comes first, never a lender's target, and we will tell you when the honest answer is no. We compare lenders, where a bank only ever offers you one. We are Brisbane based and write loans right across Australia. That is the whole pitch, no spin. General information only, not advice about your situation.
The RBA lifted rates again, the fourth rise this year
The Reserve Bank lifted the cash rate by 25 basis points to 4.60% on 29 September 2026, its fourth rise this year (source: RBA). If your repayments just went up, you don't have to just wear it. If your lender hasn't been looking after you, it may be worth checking whether your loan is still competitive. Not everyone will be better off, and we'll tell you straight if you're already on a sharp deal. If your rate just moved, send us a message and we'll run your numbers. General information only, not advice about your situation.
Is your offset account actually linked to your loan?
ASIC's review of eight banks found offset accounts that were not working properly, with the banks paying back millions of dollars to customers and most failures traced to manual errors. The riskiest moments are settlement and refinancing, which is exactly when we are involved. Once you have settled, open your banking app and check the loan: interest should be charged on the loan balance minus what is in your offset. If it is not, ring the bank. Source: ASIC Report 837, via The Broker Times, 11 September 2026. General information only, not advice about your situation.
From 1 October 2026 the ATO general interest charge on unpaid tax rises from 11.43% to 11.51% a year. It is calculated daily on what is still owing, and since 1 July 2025 it is no longer tax deductible, so the full cost stays with the taxpayer. A payment plan is not the only option. If you own property, it may be possible to clear an ATO debt with a loan secured against it, though whether that leaves you better placed depends on your situation. Source: ato.gov.au, general interest charge rates. General information only, not tax or credit advice.
First home buyers in Logan can pay no stamp duty on a brand new home
Queensland first home buyers pay no transfer duty on a brand new home, whatever the price, for contracts signed from 1 May 2025. Buying an existing home? The first home concession still removes duty below a set value threshold, then phases out above it.
The same rules apply in Logan, Ipswich, Caboolture, Redcliffe and everywhere else in Queensland. Source: Queensland Revenue Office. Eligibility rules apply, and this is general information only, not advice about your situation.
Tax debt is not a popular subject, but there is a lot of it about and people are paying a lot for it. The ATO's general interest charge on unpaid tax was 11.43% a year for July to September 2026, and it is 11.51% from 1 October 2026. It compounds daily and has not been tax deductible since 1 July 2025. Depending on your situation, refinancing or consolidating an ATO debt into property-secured lending may be an option, and there are ways to roll several debts into one and clear them sooner. If you're struggling to get ahead on your tax debt, let us know. Source: ato.gov.au. General information only, not tax or credit advice.
Watching a home go from a bare block to finished never gets old. Building soon? We look after construction loans from the deposit through every progress payment, and keep the lender, the builder and you on the same page. General information only, not advice about your situation.
A lot of homeowners tell us they would have to sell before they could do anything with their home. Not necessarily. Equity is the part of your home you already own, and it can often be used without moving anywhere.
The rough version: take what your place is worth, most lenders will look at 80% of that, then take off what you still owe. What is left is usable equity. Keep in mind an online estimate is not a valuation, and it is the lender's valuer who sets the number. Lenders assess differently and it depends on your situation, so this is general information only.
The big four banks made $30.1 billion in profit last financial year
Australia's four biggest banks reported a combined $30.1 billion in cash profit for the 2025 financial year, from mortgages like yours. If you haven't checked your home loan in a while, it's worth a look, and a mortgage health check with us costs you nothing. Source: each bank's FY2025 full year results. General information only, not advice about your situation.
Refinancing is doing much of the heavy lifting in the home loan market at the moment. The Broker Times reported on 19 August 2026 that around one in three home loans written through brokers is now a refinance rather than a purchase, with new lending volumes falling.
With fewer people buying, lenders are competing harder for borrowers who already have a loan. If nobody has reviewed your loan in a year or two, it is worth a look. This is general information only and not a quote or an offer.
Plenty of people who get in touch with us have already been told no. Sometimes that no came from a bank, sometimes from an online calculator, and sometimes from a mate who had a crack at working it out. In each case the assumption is that the answer will be the same everywhere.
It usually is not. Lenders assess income, debts and living expenses in genuinely different ways, and the same set of numbers can land very differently depending on where the application goes. A knockback from one lender tells you about that lender's policy, not about whether you can borrow at all.
If you have had a no somewhere and simply left it there, it is worth a second look. Get in touch and we will go through your situation properly.
Submitted at 7 PM, formally approved by 2 PM the next day
Nineteen hours from submission to formal approval, and construction starts shortly. We don't take it for granted when one runs like this. Most of it comes down to the file being properly packaged before it goes anywhere, so there's nothing left for the lender to come back and ask for. Not every deal moves this quickly, but they can when the groundwork's done properly. Building soon? Talk to us. General information only, not advice about your situation.
Lenders do not test you at the rate you would actually pay
Most lenders add a buffer on top of your actual rate before they work out what you can borrow. APRA's standard buffer is 3 percentage points, so a loan gets assessed as though it were 3% dearer than it really is. That is the single biggest reason an online calculator says one thing and the lender says another.
Here is the part most people do not know. Not every lender uses the full 3 percentage points. There are lenders assessing at 2%, and a couple at 1%. The rate itself usually sits a little higher on those, so it is a trade off rather than a free kick. But if borrowing power is the thing holding you back, those options exist and they are worth a look before you give up on the number.
Working out which lender suits you is most of our job. General information only, not advice about your situation. Not every borrower or loan will qualify.
The Reserve Bank held the cash rate steady at 4.35% on 11 August, and that part made the news. The part that did not was its own forecast table.
The RBA's published cash rate assumptions run 4.4% for 2026, 4.5% across 2026/27 and 2027, and 4.4% for 2028. There is no cut anywhere in it.
Waiting for rates to come down is a perfectly fair plan. It just might not be a short one. If you have parked a purchase or a refinance until things move, it is worth putting an actual number of months on that wait before you keep waiting. Source: RBA Statement on Monetary Policy, August 2026. General information only, not advice about your situation.
Same $650,000 home, three deposits: 5% is $32,500, 10% is $65,000 and 20% is $130,000. A bigger deposit means a smaller loan and lower repayments, and lenders mortgage insurance may apply under 20%. But waiting for 20% also costs you years of saving while prices move. Neither answer is automatically right. It depends on your situation, and that's the conversation worth having. General information only, not advice about your situation.
Leaving your lender is not free, and nobody mentions it until settlement. There is a discharge fee from your current lender, the new lender's setup costs, a title search, and state government fees to discharge the old mortgage and register the new one.
None of that means do not refinance. On a decent saving those costs are usually back in your pocket within months. It just means the honest question is not how good the new loan looks on paper, it is how long until you are actually in front. That is the sum we run with you before you switch.
Switch monthly to fortnightly and pay exactly half
There are 26 fortnights in a year, not 24. Pay half your monthly repayment every fortnight and you quietly make 13 monthly repayments a year instead of 12, without feeling it go out. Over a long loan, that can take years off the term. The catch: some lenders don't calculate fortnightly as exactly half, and some park the extra instead of taking it off your principal, so check before you set it up. General information only, not advice about your situation.
Sixty years ago, on 18 August 1966, a group of Australians fought at Long Tan. The part that sticks with us is what came after. A lot of them came home quietly, to a country that didn't much want to talk about where they'd been. No parade. No thanks. It took decades to start putting that right. If you know a Vietnam veteran, 18 August is a good day to pick up the phone. Lest we forget.
The monthly repayment is the number people guess at, and guessing is what stops a lot of them from starting. Our repayments calculator shows the monthly cost for your loan size, and we can run the real figures for your situation. General information only, not advice about your situation.
Saving $100 a week gets you there in about 5.8 years, $200 a week in 2.9 years, $300 a week in 1.9 years and $400 a week in 1.4 years. Most people never do this sum, they just assume a deposit is out of reach. Worked example only: a 5% deposit on a $600,000 home, straight savings, no interest counted. Eligibility rules apply. General information only, not advice about your situation.
A 5% deposit on a $600,000 home is $30,000, not $120,000. That bigger number is the one that stops most people before they even start. If you've been saving towards a number someone made up, talk to us and we'll work out your real one. Lenders mortgage insurance may apply under 20%, and eligibility rules apply. General information only, not advice about your situation.
If you've been told you need a massive deposit to get started, have a look at this. Across the first 7,200 Help to Buy applications, the median deposit was $30,000, not $130,000, and 86% of those applicants were first home buyers. The scheme has opened 10,000 new places, and the income caps went up too, to $103,000 for singles and $165,000 for couples and single parents. Here's the trade-off: the government chips in towards the purchase price, but takes an ownership share of up to 40% in return. You borrow less and need less deposit, but you don't own the whole home outright. For some people that's a great deal and for others it isn't, and there are eligibility rules and caps to work through either way. Talk to us and we'll work out which one you are. General information only, not advice about your situation.
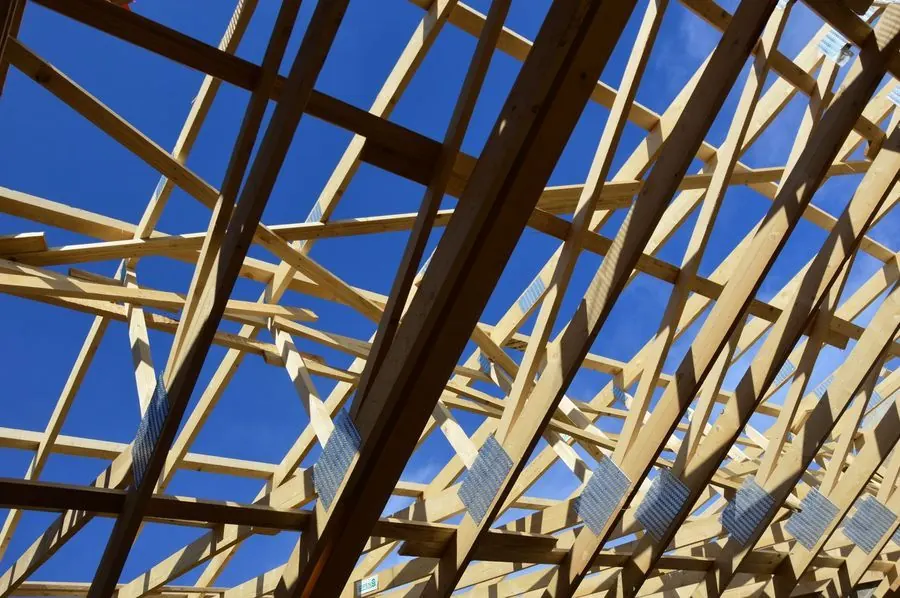
Construction is our favourite part of this job. There's something about a bare block turning into a slab, then a frame, then a roof, then someone's actual home. You get to watch the whole thing happen, and most lending isn't like that.
Jason is going through a build himself at the moment, so we've had the full experience from the other side too. Chasing invoices, lining up progress payments, working out exactly what the lender needs before it will release the next stage. It's a genuinely different animal to a standard home loan, and if nobody has walked you through it, it can feel like a lot. That's usually where we come in. Knowing what order things happen in, and what the lender wants at each stage, takes most of the stress out of it. If you're thinking about building, or you're partway through and it all feels a bit messy, give us a call.
81% of all new home loans in Australia now go through a broker instead of straight to a bank. Eight out of ten. That is not a trend anymore, that is just how most people do it.
But here is the part we reckon matters more than the milestone. Two lenders can look at the exact same person, the same income, the same deposit, and come back with very different answers. They all run their own sums, and a fair few have just reworked them. So if you have had a knock-back before, or you are going off a number someone gave you a couple of years ago, that might not be your number anymore. No pressure either way, we are happy to have a chat and tell you honestly where you stand.
Quick heads up for anyone thinking about buying property inside a self-managed super fund. From 10 August, the rules change. SMSFs will not be able to take out a new loan to buy a residential investment property.
A few things worth knowing: if your contract is signed before it starts, you are generally fine; existing SMSF loans are not affected; and commercial property is not part of this change. We are not here to tell you an SMSF is right for you, that is a proper conversation with your accountant and adviser. But if this was on your list, the window to get moving is genuinely short. If you want to talk through what is still possible, get in touch.
Everywhere you look right now the headline is the same. The market's falling. And in a couple of the big southern cities, it is. Sydney and Melbourne both dipped last month. But up here? Brisbane home values went up again, around 0.9% for the month. Perth, Adelaide and Darwin kept climbing too.
A cooling market is never really one market. It's a dozen of them, all moving at different speeds. What actually matters is what's happening in your suburb, and what it means for your borrowing power. Want to know where you really stand? Send us a message and let's take a look.
Ever noticed your bank only ever offers you its own home loan? That is the catch. Walk into one lender and you get one answer, one product, one rate, and they will never tell you if someone down the road would look after you better.
That is the whole reason a broker exists. We compare dozens of lenders, we work for you and not for them, and we go and find the one that actually fits. A fair few lenders have been sharpening their offers lately, and most of those deals are aimed at new customers rather than loyal ones, so if you have not looked at your loan in a while it is worth a fresh set of eyes. The first chat is the easy part, send us a message whenever you are ready.
Socials
Some lenders reward an efficient home
Here is one that does not get talked about enough. Some lenders will give you a sharper deal if your home is energy efficient. Solar on the roof, a battery, a strong energy rating. There is real appetite in the market for this kind of lending right now, and a few lenders have been sharpening what they put on the table for it. Two honest caveats. It will not apply to every property, and a loan is not automatically the right one for you just because it has green in the name. The benefit still has to stack up against everything else, and sometimes it does not. But if you have already got panels up, or you are weighing it up, it is worth asking the question rather than assuming the answer. We are happy to check whether your place would qualify.
Another settlement for a very happy customer, and we could not be happier for them. Getting the keys to your own place is a big moment, and being trusted to help make it happen is easily the best part of this job. If you are thinking about making a move, send us a message.
There is nothing quite like the moment someone gets the keys to their own home. All the saving, the paperwork, the "are we actually going to get there" moments, and then suddenly it is done. First home or forever home, helping people get there is exactly why we do this job.
When did you last actually look at your home loan?
Not just glance at the repayment leaving your account, but really check whether it still fits. Life moves on: incomes change, balances come down, fixed terms roll off. Refinancing is not always the answer, and we will tell you straight if you are already in a good spot.
When you walk into your own bank, they can only offer their own products. One menu, take it or leave it. We compare a whole panel of lenders to find the one that genuinely fits your situation, sometimes a big name, sometimes a lender you have never heard of that suits you far better.
Fewer people are checking their home loan, and that is exactly how borrowers end up quietly overpaying for years. When did you last give yours a health check? It costs nothing to look, and we will run the numbers for you.
Perth and Darwin are surging while Sydney and Melbourne are cooling, so where and when you buy matters more than ever. If you are weighing up your next move, or your first one, we are happy to chat about what it means for your plans.
1 in 4 Aussie mortgage holders are feeling the squeeze
If that is you, please do not sit on it. The earlier we look at your options, the more options there are. Sometimes it is a better rate, sometimes a restructure, sometimes just a plan to get ahead of it. No judgement, just a chat.
Deeper dives on the topics clients ask about most.
Afghanistan, Kandahar, 2015
Guide
The DHOAS lender panel, and why 2026 turned into a reform debate
Only a small panel of approved providers can write a DHOAS home loan. Here is what that means for an ADF borrower, what is under review, and what you can do now.
Pre-approved earlier this year? Check it again
The RBA has lifted the cash rate target four times in 2026, to 4.60% (source: RBA, rba.gov.au). Lenders test your loan at a higher rate than the one you would actually pay, so as rates rise the amount you can borrow may drop. A pre-approval from a few months back might not match what a lender would say today, and every pre-approval has an expiry date. It is much better to find that out before the auction than after, so talk to us about a fresh check. General information only, not advice about your situation.
View on Instagram: Pre-approved earlier this year? Check it againThe ATO now charges 11.51% a year on tax debt
The ATO's general interest charge on tax debt is 11.51% a year from 1 October 2026. It compounds daily, and since 1 July 2025 it can't be claimed as a tax deduction. A payment plan isn't the only way out. If you own property, it may be possible to clear an ATO debt with a loan secured against it. We look at the whole position first, then the options. Source: ato.gov.au, general interest charge rates. General information only, not advice about your situation.
View on Instagram: The ATO now charges 11.51% a year on tax debtWhy we are called Duty First
Duty First is not just a business name. We are veteran owned, and the word duty is deliberate. Your file comes first, never a lender's target, and we will tell you when the honest answer is no. We compare lenders, where a bank only ever offers you one. We are Brisbane based and write loans right across Australia. That is the whole pitch, no spin. General information only, not advice about your situation.
View on Instagram: Why we are called Duty FirstThe RBA lifted rates again, the fourth rise this year
The Reserve Bank lifted the cash rate by 25 basis points to 4.60% on 29 September 2026, its fourth rise this year (source: RBA). If your repayments just went up, you don't have to just wear it. If your lender hasn't been looking after you, it may be worth checking whether your loan is still competitive. Not everyone will be better off, and we'll tell you straight if you're already on a sharp deal. If your rate just moved, send us a message and we'll run your numbers. General information only, not advice about your situation.
View on Instagram: The RBA lifted rates again, the fourth rise this yearIs your offset account actually linked to your loan?
ASIC's review of eight banks found offset accounts that were not working properly, with the banks paying back millions of dollars to customers and most failures traced to manual errors. The riskiest moments are settlement and refinancing, which is exactly when we are involved. Once you have settled, open your banking app and check the loan: interest should be charged on the loan balance minus what is in your offset. If it is not, ring the bank. Source: ASIC Report 837, via The Broker Times, 11 September 2026. General information only, not advice about your situation.
View on Instagram: Is your offset account actually linked to your loan?ATO interest on tax debt rises from 1 October
From 1 October 2026 the ATO general interest charge on unpaid tax rises from 11.43% to 11.51% a year. It is calculated daily on what is still owing, and since 1 July 2025 it is no longer tax deductible, so the full cost stays with the taxpayer. A payment plan is not the only option. If you own property, it may be possible to clear an ATO debt with a loan secured against it, though whether that leaves you better placed depends on your situation. Source: ato.gov.au, general interest charge rates. General information only, not tax or credit advice.
View on Instagram: ATO interest on tax debt rises from 1 OctoberFirst home buyers in Logan can pay no stamp duty on a brand new home
Queensland first home buyers pay no transfer duty on a brand new home, whatever the price, for contracts signed from 1 May 2025. Buying an existing home? The first home concession still removes duty below a set value threshold, then phases out above it. The same rules apply in Logan, Ipswich, Caboolture, Redcliffe and everywhere else in Queensland. Source: Queensland Revenue Office. Eligibility rules apply, and this is general information only, not advice about your situation.
View on Instagram: First home buyers in Logan can pay no stamp duty on a brand new homeTax debt: the ATO's interest keeps compounding
Tax debt is not a popular subject, but there is a lot of it about and people are paying a lot for it. The ATO's general interest charge on unpaid tax was 11.43% a year for July to September 2026, and it is 11.51% from 1 October 2026. It compounds daily and has not been tax deductible since 1 July 2025. Depending on your situation, refinancing or consolidating an ATO debt into property-secured lending may be an option, and there are ways to roll several debts into one and clear them sooner. If you're struggling to get ahead on your tax debt, let us know. Source: ato.gov.au. General information only, not tax or credit advice.
View on Instagram: Tax debt: the ATO's interest keeps compoundingAnother new build, finished
Watching a home go from a bare block to finished never gets old. Building soon? We look after construction loans from the deposit through every progress payment, and keep the lender, the builder and you on the same page. General information only, not advice about your situation.
View on Instagram: Another new build, finishedYou may not need to sell to use your equity
A lot of homeowners tell us they would have to sell before they could do anything with their home. Not necessarily. Equity is the part of your home you already own, and it can often be used without moving anywhere. The rough version: take what your place is worth, most lenders will look at 80% of that, then take off what you still owe. What is left is usable equity. Keep in mind an online estimate is not a valuation, and it is the lender's valuer who sets the number. Lenders assess differently and it depends on your situation, so this is general information only.
View on Instagram: You may not need to sell to use your equityThe big four banks made $30.1 billion in profit last financial year
Australia's four biggest banks reported a combined $30.1 billion in cash profit for the 2025 financial year, from mortgages like yours. If you haven't checked your home loan in a while, it's worth a look, and a mortgage health check with us costs you nothing. Source: each bank's FY2025 full year results. General information only, not advice about your situation.
View on Instagram: The big four banks made $30.1 billion in profit last financial yearOne in three broker home loans is now a refinance
Refinancing is doing much of the heavy lifting in the home loan market at the moment. The Broker Times reported on 19 August 2026 that around one in three home loans written through brokers is now a refinance rather than a purchase, with new lending volumes falling. With fewer people buying, lenders are competing harder for borrowers who already have a loan. If nobody has reviewed your loan in a year or two, it is worth a look. This is general information only and not a quote or an offer.
View on Instagram: One in three broker home loans is now a refinanceA no from one lender is not a no from all of them
Plenty of people who get in touch with us have already been told no. Sometimes that no came from a bank, sometimes from an online calculator, and sometimes from a mate who had a crack at working it out. In each case the assumption is that the answer will be the same everywhere. It usually is not. Lenders assess income, debts and living expenses in genuinely different ways, and the same set of numbers can land very differently depending on where the application goes. A knockback from one lender tells you about that lender's policy, not about whether you can borrow at all. If you have had a no somewhere and simply left it there, it is worth a second look. Get in touch and we will go through your situation properly.
View on Instagram: A no from one lender is not a no from all of themSubmitted at 7 PM, formally approved by 2 PM the next day
Nineteen hours from submission to formal approval, and construction starts shortly. We don't take it for granted when one runs like this. Most of it comes down to the file being properly packaged before it goes anywhere, so there's nothing left for the lender to come back and ask for. Not every deal moves this quickly, but they can when the groundwork's done properly. Building soon? Talk to us. General information only, not advice about your situation.
View on Instagram: Submitted at 7 PM, formally approved by 2 PM the next dayLenders do not test you at the rate you would actually pay
Most lenders add a buffer on top of your actual rate before they work out what you can borrow. APRA's standard buffer is 3 percentage points, so a loan gets assessed as though it were 3% dearer than it really is. That is the single biggest reason an online calculator says one thing and the lender says another. Here is the part most people do not know. Not every lender uses the full 3 percentage points. There are lenders assessing at 2%, and a couple at 1%. The rate itself usually sits a little higher on those, so it is a trade off rather than a free kick. But if borrowing power is the thing holding you back, those options exist and they are worth a look before you give up on the number. Working out which lender suits you is most of our job. General information only, not advice about your situation. Not every borrower or loan will qualify.
View on Instagram: Lenders do not test you at the rate you would actually payThe RBA's own forecast has no cut in it
The Reserve Bank held the cash rate steady at 4.35% on 11 August, and that part made the news. The part that did not was its own forecast table. The RBA's published cash rate assumptions run 4.4% for 2026, 4.5% across 2026/27 and 2027, and 4.4% for 2028. There is no cut anywhere in it. Waiting for rates to come down is a perfectly fair plan. It just might not be a short one. If you have parked a purchase or a refinance until things move, it is worth putting an actual number of months on that wait before you keep waiting. Source: RBA Statement on Monetary Policy, August 2026. General information only, not advice about your situation.
View on Instagram: The RBA's own forecast has no cut in itShould you wait until you've got a 20% deposit?
Same $650,000 home, three deposits: 5% is $32,500, 10% is $65,000 and 20% is $130,000. A bigger deposit means a smaller loan and lower repayments, and lenders mortgage insurance may apply under 20%. But waiting for 20% also costs you years of saving while prices move. Neither answer is automatically right. It depends on your situation, and that's the conversation worth having. General information only, not advice about your situation.
View on Instagram: Should you wait until you've got a 20% deposit?The exit fee nobody mentions
Leaving your lender is not free, and nobody mentions it until settlement. There is a discharge fee from your current lender, the new lender's setup costs, a title search, and state government fees to discharge the old mortgage and register the new one. None of that means do not refinance. On a decent saving those costs are usually back in your pocket within months. It just means the honest question is not how good the new loan looks on paper, it is how long until you are actually in front. That is the sum we run with you before you switch.
View on Instagram: The exit fee nobody mentionsSwitch monthly to fortnightly and pay exactly half
There are 26 fortnights in a year, not 24. Pay half your monthly repayment every fortnight and you quietly make 13 monthly repayments a year instead of 12, without feeling it go out. Over a long loan, that can take years off the term. The catch: some lenders don't calculate fortnightly as exactly half, and some park the extra instead of taking it off your principal, so check before you set it up. General information only, not advice about your situation.
View on Instagram: Switch monthly to fortnightly and pay exactly halfVietnam Veterans' Day: 60 years since Long Tan
Sixty years ago, on 18 August 1966, a group of Australians fought at Long Tan. The part that sticks with us is what came after. A lot of them came home quietly, to a country that didn't much want to talk about where they'd been. No parade. No thanks. It took decades to start putting that right. If you know a Vietnam veteran, 18 August is a good day to pick up the phone. Lest we forget.
View on Instagram: Vietnam Veterans' Day: 60 years since Long TanWhat would a home loan cost you each month?
The monthly repayment is the number people guess at, and guessing is what stops a lot of them from starting. Our repayments calculator shows the monthly cost for your loan size, and we can run the real figures for your situation. General information only, not advice about your situation.
View on Instagram: What would a home loan cost you each month?How long does a $30,000 deposit take to save?
Saving $100 a week gets you there in about 5.8 years, $200 a week in 2.9 years, $300 a week in 1.9 years and $400 a week in 1.4 years. Most people never do this sum, they just assume a deposit is out of reach. Worked example only: a 5% deposit on a $600,000 home, straight savings, no interest counted. Eligibility rules apply. General information only, not advice about your situation.
View on Instagram: How long does a $30,000 deposit take to save?You don't need a $100k deposit
A 5% deposit on a $600,000 home is $30,000, not $120,000. That bigger number is the one that stops most people before they even start. If you've been saving towards a number someone made up, talk to us and we'll work out your real one. Lenders mortgage insurance may apply under 20%, and eligibility rules apply. General information only, not advice about your situation.
View on Instagram: You don't need a $100k depositHelp to Buy: the median deposit was $30,000
If you've been told you need a massive deposit to get started, have a look at this. Across the first 7,200 Help to Buy applications, the median deposit was $30,000, not $130,000, and 86% of those applicants were first home buyers. The scheme has opened 10,000 new places, and the income caps went up too, to $103,000 for singles and $165,000 for couples and single parents. Here's the trade-off: the government chips in towards the purchase price, but takes an ownership share of up to 40% in return. You borrow less and need less deposit, but you don't own the whole home outright. For some people that's a great deal and for others it isn't, and there are eligibility rules and caps to work through either way. Talk to us and we'll work out which one you are. General information only, not advice about your situation.
View on Instagram: Help to Buy: the median deposit was $30,000Nothing beats watching a frame go up
Construction is our favourite part of this job. There's something about a bare block turning into a slab, then a frame, then a roof, then someone's actual home. You get to watch the whole thing happen, and most lending isn't like that. Jason is going through a build himself at the moment, so we've had the full experience from the other side too. Chasing invoices, lining up progress payments, working out exactly what the lender needs before it will release the next stage. It's a genuinely different animal to a standard home loan, and if nobody has walked you through it, it can feel like a lot. That's usually where we come in. Knowing what order things happen in, and what the lender wants at each stage, takes most of the stress out of it. If you're thinking about building, or you're partway through and it all feels a bit messy, give us a call.
View on Instagram: Nothing beats watching a frame go upBrokers just hit a record
81% of all new home loans in Australia now go through a broker instead of straight to a bank. Eight out of ten. That is not a trend anymore, that is just how most people do it. But here is the part we reckon matters more than the milestone. Two lenders can look at the exact same person, the same income, the same deposit, and come back with very different answers. They all run their own sums, and a fair few have just reworked them. So if you have had a knock-back before, or you are going off a number someone gave you a couple of years ago, that might not be your number anymore. No pressure either way, we are happy to have a chat and tell you honestly where you stand.
View on Instagram: Brokers just hit a recordA quiet deadline for SMSF buyers
Quick heads up for anyone thinking about buying property inside a self-managed super fund. From 10 August, the rules change. SMSFs will not be able to take out a new loan to buy a residential investment property. A few things worth knowing: if your contract is signed before it starts, you are generally fine; existing SMSF loans are not affected; and commercial property is not part of this change. We are not here to tell you an SMSF is right for you, that is a proper conversation with your accountant and adviser. But if this was on your list, the window to get moving is genuinely short. If you want to talk through what is still possible, get in touch.
View on Instagram: A quiet deadline for SMSF buyersThe market's falling? Not up here.
Everywhere you look right now the headline is the same. The market's falling. And in a couple of the big southern cities, it is. Sydney and Melbourne both dipped last month. But up here? Brisbane home values went up again, around 0.9% for the month. Perth, Adelaide and Darwin kept climbing too. A cooling market is never really one market. It's a dozen of them, all moving at different speeds. What actually matters is what's happening in your suburb, and what it means for your borrowing power. Want to know where you really stand? Send us a message and let's take a look.
View on Instagram: The market's falling? Not up here.Your bank can only offer you one loan
Ever noticed your bank only ever offers you its own home loan? That is the catch. Walk into one lender and you get one answer, one product, one rate, and they will never tell you if someone down the road would look after you better. That is the whole reason a broker exists. We compare dozens of lenders, we work for you and not for them, and we go and find the one that actually fits. A fair few lenders have been sharpening their offers lately, and most of those deals are aimed at new customers rather than loyal ones, so if you have not looked at your loan in a while it is worth a fresh set of eyes. The first chat is the easy part, send us a message whenever you are ready.
Some lenders reward an efficient home
Here is one that does not get talked about enough. Some lenders will give you a sharper deal if your home is energy efficient. Solar on the roof, a battery, a strong energy rating. There is real appetite in the market for this kind of lending right now, and a few lenders have been sharpening what they put on the table for it. Two honest caveats. It will not apply to every property, and a loan is not automatically the right one for you just because it has green in the name. The benefit still has to stack up against everything else, and sometimes it does not. But if you have already got panels up, or you are weighing it up, it is worth asking the question rather than assuming the answer. We are happy to check whether your place would qualify.
View on Instagram: Some lenders reward an efficient homeAnother one settled
Another settlement for a very happy customer, and we could not be happier for them. Getting the keys to your own place is a big moment, and being trusted to help make it happen is easily the best part of this job. If you are thinking about making a move, send us a message.
View on Instagram: Another one settledOne day, the keys are yours
There is nothing quite like the moment someone gets the keys to their own home. All the saving, the paperwork, the "are we actually going to get there" moments, and then suddenly it is done. First home or forever home, helping people get there is exactly why we do this job.
View on Instagram: One day, the keys are yoursWhen did you last actually look at your home loan?
Not just glance at the repayment leaving your account, but really check whether it still fits. Life moves on: incomes change, balances come down, fixed terms roll off. Refinancing is not always the answer, and we will tell you straight if you are already in a good spot.
View on Instagram: When did you last actually look at your home loan?Your bank is not your only option
When you walk into your own bank, they can only offer their own products. One menu, take it or leave it. We compare a whole panel of lenders to find the one that genuinely fits your situation, sometimes a big name, sometimes a lender you have never heard of that suits you far better.
View on Instagram: Your bank is not your only optionRefinancing activity has dropped 5.6% this year
Fewer people are checking their home loan, and that is exactly how borrowers end up quietly overpaying for years. When did you last give yours a health check? It costs nothing to look, and we will run the numbers for you.
View on Instagram: Refinancing activity has dropped 5.6% this yearAustralia is running a two-speed property market
Perth and Darwin are surging while Sydney and Melbourne are cooling, so where and when you buy matters more than ever. If you are weighing up your next move, or your first one, we are happy to chat about what it means for your plans.
View on Instagram: Australia is running a two-speed property market1 in 4 Aussie mortgage holders are feeling the squeeze
If that is you, please do not sit on it. The earlier we look at your options, the more options there are. Sometimes it is a better rate, sometimes a restructure, sometimes just a plan to get ahead of it. No judgement, just a chat.
View on Instagram: 1 in 4 Aussie mortgage holders are feeling the squeeze